SIM-Only With No Credit Check: Your Options as a New Arrival in the UK
Last updated: 7 November 2026 | Next review due: 7 February 2027
SimSaver may earn a commission if you buy through links on this page. This never changes how we rank or describe a deal; see how we compare.
Key takeaways
- You do not need a UK credit history to get a UK number. Pay as you go (PAYG) on networks such as EE, Vodafone and Three, and monthly no-contract plans from brands such as giffgaff, SMARTY and Lebara, come without a credit check.
- Do not assume "SIM-only" means "no check". iD Mobile checks every SIM-only application, and Lyca Mobile checks its pay monthly SIM deals.
- Three, for example, notes failed checks on its records and says they may affect your credit rating, so start with a no-check plan instead of applying for contracts one after another.
- Check your phone before you buy: it must be unlocked and able to make calls over 4G, because 3G has been switched off across the UK.
- You do not need a contract. Rolling plans are often cheaper once you add the annual rises most contracts carry.
The short answer
Short answer
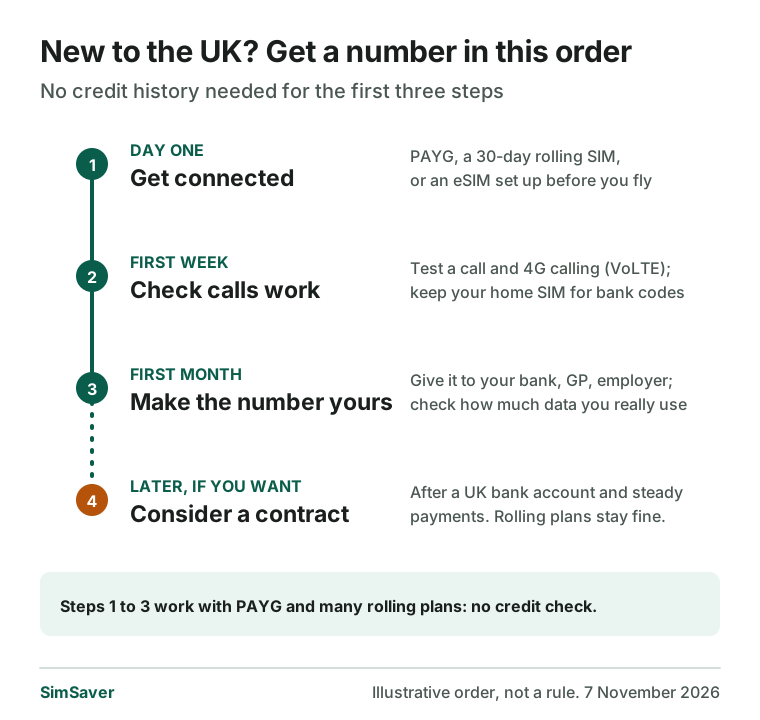
- Arriving in the next few weeks: order a SIM from a provider that posts abroad (giffgaff does), set up an eSIM, or buy a PAYG SIM at the airport or a supermarket. No credit check.
- Settling in: move to a monthly no-contract plan (no credit check at giffgaff, SMARTY, Lebara, VOXI and others) sized to the data you actually use.
- Keep your home SIM in the phone as a second line for bank codes, and switch its data roaming off.
- Later, if a contract is clearly cheaper, apply once you have a UK bank account, your address on record and a few months of on-time payments.
Why newcomers get refused
A UK credit check looks only at UK records. Experian, one of the three credit reference agencies, says a good credit history overseas won't help you in the UK, so you start from scratch. To a lender, having no file looks much like having a poor one, because there is nothing to go on.
Some providers say so directly. Three lists not having lived in the UK for three years or more as an example of why a Pay Monthly check might fail. It also needs a UK bank account for the Direct Debit, may ask for a deposit, and warns against resubmitting orders after a failure, because failed checks are noted and may affect your credit rating. If you are refused, Three offers pay as you go instead.
So a refusal does not stop you getting a number. It just means starting on pay as you go or a no-check plan.
Which deals are credit-checked
The table shows what each provider's own page says, plus a consumer-advice site's guide to one-month plans for VOXI. It was checked on 7 November 2026. Checks can change, so confirm before you apply.
SimSaver may earn a commission on links here; this never changes how we rank.
| Provider | Monthly plan without a long contract | Pay as you go |
|---|---|---|
| Asda Mobile | No credit check and no contracts; bundles last one calendar month | Same bundles |
| giffgaff | No credit check on plans; a check only if you buy a phone on a loan (run by Klarna) | No check |
| Honest Mobile | No credit checks | Not offered |
| Lebara | No credit check | Not offered |
| SMARTY | No credit check, because you pay upfront; rolling plans from £6 | Not offered |
| VOXI | No credit check on SIM plans (according to a consumer-advice site's guide); phones bought on credit are checked | Not offered |
| iD Mobile | Credit checked: all SIM-only applications, through Equifax | No check |
| Lyca Mobile | Credit checked (pay monthly SIM-only, including one-month plans) | No check |
| Three | Pay Monthly is credit checked | No check |
How we compare. We grouped providers by whether their monthly plans are credit checked, then listed brands alphabetically within each group, with the credit-checked brands last. We used providers' own pages where they loaded and, for VOXI, a consumer-advice site's guide to one-month plans (dated 6 November 2026). We checked everything on 7 November 2026. Provider pages are the final authority, and policies change. We do not rank by commission.
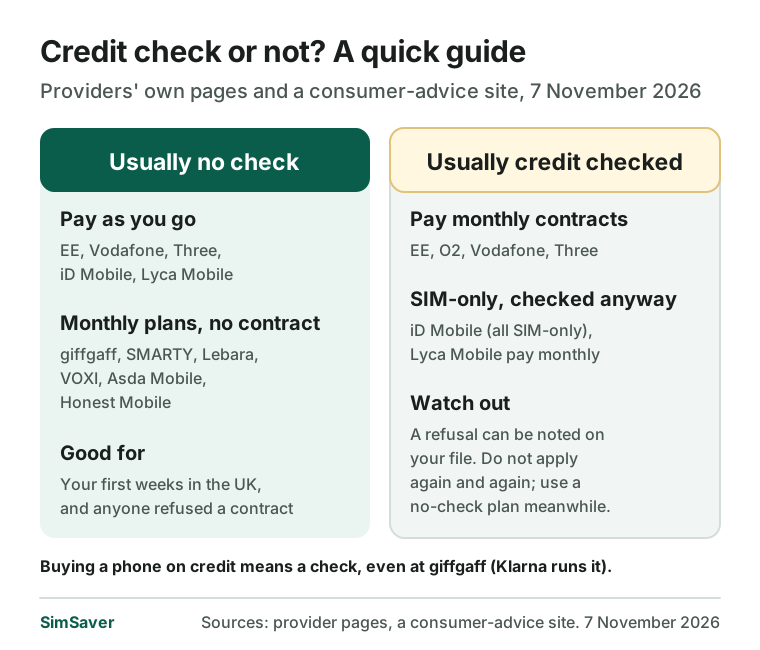
Brands that skip checks usually take payment upfront by card rather than by Direct Debit; SMARTY gives exactly that reason. And a few names you might expect to be easy are not: iD Mobile checks all SIM-only applications, and Lyca Mobile checks its pay monthly SIM deals, including one-month plans.
PAYG or a rolling monthly plan?
Both work without a UK credit history. The difference is how you pay and what you get for it.
Pay as you go means you top up credit or buy a bundle when you need it. It is the quickest way to get connected and has no monthly bill. The catch is that bundles on the big networks can be dearer than the cheapest rolling plans, and some PAYG plans leave out features: check the bundle details for 5G, Wi-Fi calling and any speed limits.
A rolling monthly plan (often called 30-day or one-month SIM-only) takes a payment every month and renews until you cancel. You can usually change the size of the plan or leave at the end of any month. This suits most newcomers: no credit check at the brands listed above, no commitment, and prices that start low. SMARTY's rolling plans start from £6, and a consumer-advice site's listings of one-month plans on 6 November 2026 included 5GB plans for under £5 a month from spusu and Talkmobile. We have not confirmed whether these two brands credit check, so check before you apply. Prices are illustrative and change often; check the price after any introductory months.
A sensible pattern: get connected on whatever is quickest, watch how much data you use for a few weeks, then move to a rolling plan that fits. Moving is easy and you can keep your new UK number; our switching guide shows how.
Getting a SIM before you fly or on the day you land
The airport is not your only option.
Before you travel. giffgaff posts SIMs abroad, taking about three to five working days to Europe and longer elsewhere. An eSIM avoids the post altogether: giffgaff activates its eSIM in its app only and needs an unlocked phone. Some services only start once you are in the UK; VOXI, for example, says you need to be in the UK to start using your SIM.
At the airport. Heathrow lists SIM card shops across Terminals 2 to 5, and travel sites report SIM vending machines at Gatwick. It is convenient, but the University of Warwick's advice to new students notes airport SIMs may be more expensive than buying elsewhere. If you buy one, treat it as a bridge for the first week rather than your long-term plan.
In town or on campus. Supermarkets such as Tesco and the Co-op sell PAYG SIMs. Some universities hand out free SIMs in welcome week; Warwick did so from 22 September 2026.
Paying for it. No-check brands generally take card payments. SMARTY, for instance, accepts debit and credit cards, PayPal, Apple Pay, Google Pay and cash at PayPoint, but not Direct Debit. We could not confirm whether each brand accepts cards issued abroad, so if your first payment fails, try another card or a UK account once you have one.
Check your phone first
A cheap SIM is no use if your phone cannot make calls on UK networks. Do these two checks before you buy anything.
Is it unlocked? Phones bought on a contract abroad are often locked to that network. Warwick advises checking, and contacting your home provider if it is locked. In the UK, providers have been banned from selling locked phones since December 2021, but that rule does not cover phones sold elsewhere.
Can it call over 4G? The UK's 3G networks have been switched off, so voice calls now rely on 4G calling (VoLTE, voice over LTE), with 2G as a fading fallback on some networks. Ofcom notes that Three has no 2G network at all. Support depends on the phone model and the network: EE says it cannot guarantee that phones bought from third parties support 4G calling, and giffgaff publishes a list of compatible models (updated 30 September 2026), including iPhone XR and later on iOS 17.4 or later, Pixel 7 and later, and Xiaomi phones with Snapdragon chips. If your model is not on a network's list, choose a different network or test with a cheap PAYG SIM first.
The quickest test on day one: make a normal call, then check that the network indicator still shows 4G or 5G during the call. Our eSIM guide covers compatibility for eSIM-only phones.
One safety point from Warwick's guidance: you can call 999 or 112 from any phone, but if your SIM is not on a UK network, emergency services may not be able to call you back if the call drops. That alone is a good reason to get a UK number quickly.
Keep your home number without paying roaming
Most people still need their home number for a while, for banking codes, family and accounts back home. The cleanest set-up is a dual-SIM phone with your UK SIM as the main line and your home SIM as the second line, with data roaming switched off on the home SIM. If your phone has one physical slot, move one of the two numbers to an eSIM.
Before you rely on it, check your home operator's prices for the UK. Since Brexit the UK is outside EU "roam like at home" rules, so EU operators set their own UK rates.
Optional: a Polish number in the UK
A telecoms news site reported that from 1 July 2026 to 31 January 2027 Plus charges 0.99 zł a minute for calls made or received in the UK, and 59 zł per GB on plans such as Giga Plus (99 zł per GB on prepaid). Other Polish operators have their own UK prices and promotions. Whatever your operator, keep the Polish SIM mainly for receiving texts such as bank codes, and do everything else on the UK line or over Wi-Fi. Our guide to cheap calls from the UK covers calling family abroad.
Building UK credit, if you want a contract later
You may never need a mobile contract. But if you want one, or want a mortgage, a credit card or a phone on finance later, the same steps help. Experian suggests:
- Register to vote if you can. It helps lenders confirm your name and address. Eligibility depends on nationality and where you live. In England and Northern Ireland, GOV.UK lists Commonwealth citizens and citizens of Denmark, Luxembourg, Poland, Portugal and Spain with permission to stay, and other EU citizens only if they had permission on or before 31 December 2020. Scotland and Wales use a broader permission-to-stay test.
- Open a UK bank account and use it well. If a standard account is refused, a basic bank account is the fallback.
- Add other regular payments. Rent can be added through a rent-reporting service, usually after about six months of payments, and some household bills paid monthly are also reported.
- Ask to move from PAYG to monthly. Experian suggests asking your mobile provider after a period of consistent payments, and trying again a few months later if refused.
- Give it time. Experian says new accounts can take up to six months to build enough history for a score.
There is no fixed point at which a newcomer "passes". Each provider uses its own criteria, which is why one application, made when your file has something on it, beats several made in your first month.
A note on immigration documents. GOV.UK says all biometric residence permits have expired and been replaced by eVisas. An expired BRP can still be used, until 31 December 2026 at the latest, only to view your eVisa and get a share code, create a UKVI account or apply to extend your stay. The no-check mobile plans in this guide do not ask for immigration documents, as far as their pages show, but landlords in England and employers may ask for a share code from your eVisa.
Scams to watch for in your first months
New arrivals get targeted, often by phone. The UK Council for International Student Affairs warns about fake Home Office calls demanding "fines", sometimes with a callback number that looks genuine; the Home Office does not issue fines like this. A visa-expiry reminder can be genuine, but one that asks you to reply, share details or pay is a scam. Hang up and contact the organisation through its official website.
Your new number is also worth protecting. Fraud prevention service Cifas reported that unauthorised SIM swaps rose by 1,055 per cent in 2024, to almost 3,000 cases. Set a PIN or password on your mobile account, and treat any unexpected text about a SIM change or a PAC code as a warning sign.
Report fraud to Report Fraud, which replaced Action Fraud in England, Wales and Northern Ireland from December 2025 (0300 123 2040, reportfraud.police.uk). In Scotland, call Police Scotland on 101.
Worked example: three newcomers, three set-ups
Prices are illustrative, for comparison only.
| Person | Set-up | Cost |
|---|---|---|
| A. Student arriving in September, light data use, mostly on campus Wi-Fi | Free welcome-week SIM used for a rolling plan at £6 a month | 12 x £6 = £72 a year |
| B. New arrival from Poland who calls home often | Rolling 30GB-type plan at £10 a month on the UK line; Polish SIM kept as a second line with data roaming off | 12 x £10 = £120 a year on the UK line, plus only the occasional Polish roaming charge |
| C. British citizen back after ten years abroad, refused a contract | Rolling plan for six months while building a credit file, then compare a contract | 6 x £6 = £36 for the first six months; no failed applications on file |
Is a contract worth it? Say person B is offered a 24-month contract at £8 a month with £2.50 rises each April, starting in November. Over 24 months that is 5 x £8 + 12 x £10.50 + 7 x £13 = £257, against £240 for the £10 rolling plan, assuming its price stays the same. The "cheaper" contract costs £17 more, before counting the freedom to leave. Our guide to mobile price rises explains how to run this sum for any deal.
Common mistakes
- Applying for several contracts in your first week. Failed checks can be recorded and may affect your credit rating. Start with a no-check plan.
- Assuming every SIM-only deal skips the check. iD Mobile and Lyca Mobile check theirs.
- Buying a SIM before checking the phone. Locked phones and phones without UK 4G calling cause most "my SIM doesn't work" problems.
- Living on the airport SIM. Fine for the first week; usually dearer after that.
- Roaming on your home SIM. Switch its data roaming off and use it for texts only.
- Forgetting to update your records. Give your new number to your bank, GP, employer or university as soon as you have it.
FAQ
Can I get a UK SIM card without a credit check?
Yes. Pay as you go SIMs on networks such as EE, Vodafone and Three, and monthly no-contract plans from brands such as giffgaff, SMARTY, Lebara, VOXI and Asda Mobile, do not involve a credit check. Check each provider's page before you apply, because some SIM-only plans, such as iD Mobile's, are credit checked.
Why was I refused a phone contract when I have good credit abroad?
UK credit checks use UK records only, so an overseas history does not count. Three, for example, gives not having lived in the UK for three years as one reason a check might fail. Use a no-check plan while you build a UK file.
What is the difference between pay as you go and SIM-only?
Pay as you go means topping up or buying bundles when you need them, with no monthly bill. SIM-only means a monthly plan without a phone; it can be a rolling plan you can leave any month or a fixed contract, which is usually credit checked.
Can I get a UK SIM before I arrive?
Often, yes. giffgaff posts SIMs abroad, and several providers offer eSIMs you can set up in an app. Some, such as VOXI, only let you start using the SIM once you are in the UK.
Will my phone from abroad work in the UK?
It needs to be unlocked and to support 4G calling (VoLTE) on your chosen UK network, because 3G has been switched off. Check the network's list of compatible phones, or test with a cheap pay as you go SIM first.
Does a SIM-only plan build my credit score?
We could not confirm that rolling no-check plans are reported to credit reference agencies. Pay monthly contracts are credit agreements that providers share information about, so they can build history. Experian suggests asking to move from pay as you go to a monthly contract after a period of steady payments.
How long does it take to build a UK credit history?
There is no fixed time. Experian says new accounts can take up to six months to build enough history for a score, and registering to vote, if you are eligible, helps lenders confirm your address.
Keep reading
- How to choose the right SIM card in the UK: the full method once you are settled.
- eSIM in the UK: the complete guide: set up a UK eSIM and keep your home number on the same phone.
- How to save money on mobile data and calls: cheap ways to call family abroad.
- Mobile price rises: what each network is adding: why a rolling plan can beat a "cheaper" contract.
- How to switch mobile provider and keep your number: move to a better plan without losing your new UK number.
Sources
This guide is based on official and primary sources: GOV.UK, Ofcom, Experian, UKCISA, Cifas, City of London Police, the University of Warwick, Heathrow Airport and the providers' own published pages (Three, giffgaff, SMARTY, Asda Mobile, Honest Mobile, Lyca Mobile, iD Mobile, EE and the other providers named in the text). All were accessed on 7 November 2026. Where a detail comes from a consumer-advice site or a telecoms news site and not from an official page, the text says so.